For payments you make in 2026, you generally must file a Form 1099-NEC once you have paid a contractor $2,000 or more for services in the year. The old trigger was $600. The forms are due in early 2027, and a few situations, such as backup withholding, ignore the dollar threshold altogether. This guide walks through who gets a form, which form to use, when it is due, and what to set up now so January is not a scramble.
TL;DR
- Threshold: for payments made in 2026, the reporting threshold for Form 1099-NEC is $2,000, up from $600. It is adjusted for inflation starting in 2027.
- Deadline: the 2026 Form 1099-NEC is due to the IRS and to the recipient on January 31, 2027. Because that date is a Sunday, the next business day, Monday, February 1, 2027, counts as timely.
- Who gets one: non-employees you paid for services in the course of your trade or business, including attorneys. Personal payments are not reportable.
- Exceptions: if you withheld any federal income tax (backup withholding) from a payee, you file regardless of the amount. And if you have 10 or more information returns, you must e-file.
What the 1099-NEC reports
Form 1099-NEC reports nonemployee compensation: money you paid to someone who is not your employee for services they performed for your business. Think freelance designers, consultants, independent contractors, subcontractors, and attorneys whose fees you paid.
The form came back in 2020 to separate contractor pay from the miscellaneous items that stay on the 1099-MISC. That split still drives the most confusion for small businesses, so it gets its own section below.
The IRS states that reporting applies to payments made in the course of a trade or business. Nonprofits count as engaged in a trade or business for this purpose, so a nonprofit that pays a contractor to run its events or its website has the same obligation as a for-profit company. Payments for personal reasons, such as hiring a painter for your own house, are not reportable.
The 2026 threshold: from $600 to $2,000
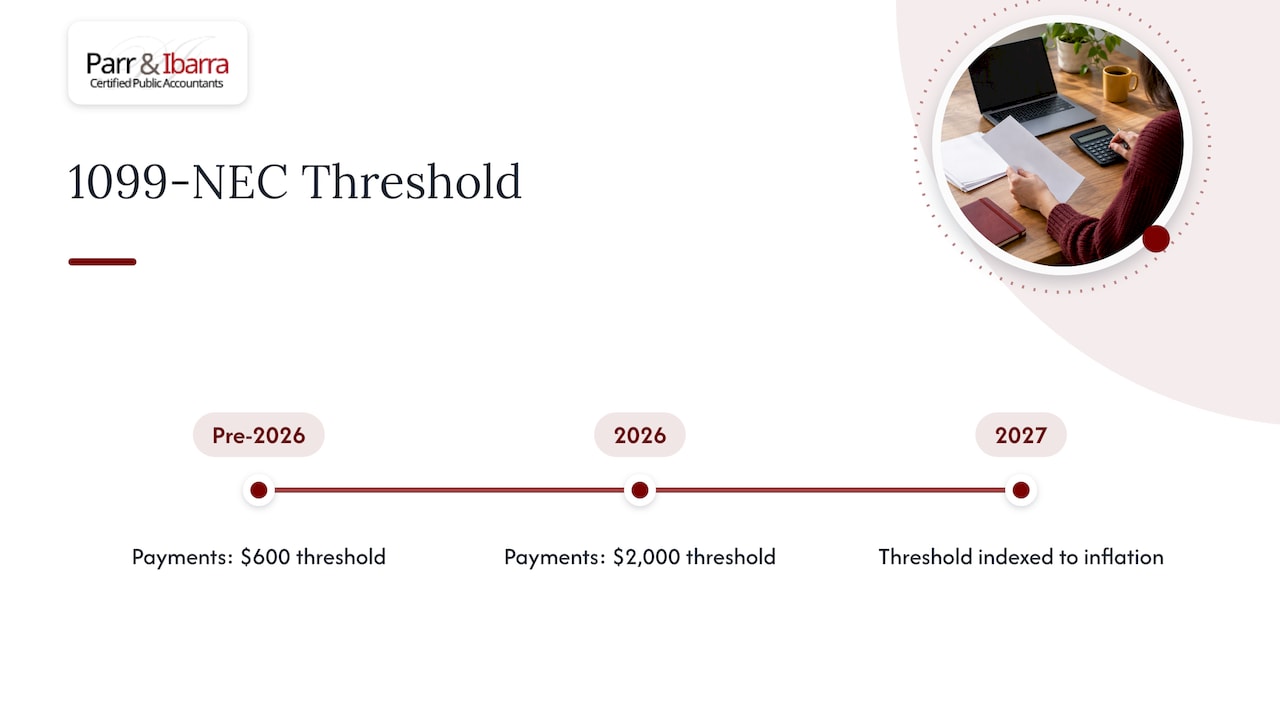
The change comes from the One, Big, Beautiful Bill Act. For payments made before 2026 the threshold was $600. For payments made in 2026, the IRS instructions put it at $2,000, and it will be indexed to inflation beginning in calendar year 2027.
A few practical points follow from that.
It is a calendar-year total per payee. You add up everything you paid one contractor in 2026 for services. Three invoices of $800 to the same freelancer is $2,400, so a form is required. One payment of $1,900 is not.
The old number may still be in your software. Many accounting and payroll tools default to $600. If you export a contractor list in December and trust the default, you may over-report. The IRS notes that you can choose to keep reporting smaller amounts if that simplifies your process, but you are not required to.
Payments made in 2025 still use $600. Forms filed in early 2026 covered 2025 payments under the old rule. The 2026 change shows up for the first time in the forms you file in early 2027.
The threshold does not help you with everything. Some categories keep lower triggers. For example, the IRS lists royalties of at least $10 for Form 1099-MISC, and backup withholding, covered below, has no minimum.
Who gets a 1099-NEC
Use this checklist for each person or business you paid in 2026.
- Did you pay them for services? Product purchases and reimbursements generally are not nonemployee compensation.
- Was it in the course of your trade or business? Personal payments are out.
- Is the payee a contractor, not an employee? Employees get a W-2. If you are unsure how a worker is classified, resolve that before year-end, because misclassification creates problems well beyond a missing form.
- Did total payments reach $2,000 in 2026? If yes, file. If no, you generally do not, unless backup withholding applies.
- Did you withhold any federal income tax from them? If so, you must file a 1099-NEC no matter how small the payment was.
Attorneys
Payments to attorneys for legal services are covered by the same $2,000 threshold. If you paid a law firm and nothing else, check that you are filing on the right form and box, since certain gross-proceeds payments to attorneys are reported differently.
Corporations and LLCs
Contractors who operate as corporations are often exempt from receiving a 1099-NEC, but there are exceptions, attorneys being the most common. Rather than guess, collect a Form W-9 from every contractor before you pay them. It records the legal name, tax classification and taxpayer ID you need, and it gives you the evidence if the IRS questions why you did or did not file.
Payments by card or payment app
If you paid a contractor with a credit card or through a third-party payment network, the card processor or network usually reports that payment on Form 1099-K, and you generally do not also report it on a 1099-NEC. Confirm the rule for your situation in the IRS instructions before you skip a form.
1099-NEC vs. 1099-MISC
This is the question readers search most, and the short answer is: services go on the NEC, other specific income types go on the MISC.
| 1099-NEC | 1099-MISC | |
|---|---|---|
| What it reports | Nonemployee compensation for services | Rents, royalties, prizes, other income, and certain other payments |
| 2026 threshold | $2,000 for most reportable services | $2,000 for most categories, with exceptions such as royalties at $10 |
| Federal due date | Single deadline for paper and electronic | Later deadlines: February 28 on paper, March 31 if filed electronically |
| Recipient copy | Same deadline as the IRS filing | Generally earlier than the IRS e-file date |
A few details from the IRS instructions are worth keeping in mind:
- Direct sales of consumer products of $5,000 or more can be reported on either the 1099-NEC (box 2) or the 1099-MISC (box 7), but not both. Choosing the NEC pulls the deadline forward to January 31. Pick one method and use it consistently.
- Rent paid to a landlord is a 1099-MISC item, not a 1099-NEC item, even if the landlord also does some work for you. Keep the two types of payment separate in your books.
- Cash tips and overtime compensation: the IRS has updated the forms so Forms 1099-MISC and 1099-NEC allow reporting of cash tips, the Treasury Tipped Occupation Code and overtime compensation. If your business pays tipped workers or deals with these reporting items, ask your CPA how the new boxes apply to you.
1099 due dates for 2026 payments
For the 2026 tax year, the Form 1099-NEC filing and furnishing deadline is January 31, 2027, and that applies whether you file on paper or electronically. When the date lands on a weekend or legal holiday, filing on the next business day is timely. January 31, 2027 is a Sunday, so plan for Monday, February 1, 2027 at the latest, and aim to finish well before.
There is no automatic extension. That is the difference from many other tax forms, and it is why a contractor list built in January is already late. Build it in December.
| Item | Date for 2026 payments |
|---|---|
| Form 1099-NEC to contractor and to the IRS | January 31, 2027 (effectively Monday, February 1, 2027) |
| Form 1099-MISC, paper filing with the IRS | February 28 |
| Form 1099-MISC, electronic filing with the IRS | March 31 |
If a state where you do business has its own 1099 filing or withholding rules, those dates and requirements are separate from the federal ones. Check with the state’s revenue agency or ask your CPA.
E-filing: the 10-return rule
If you file 10 or more information returns in total, you must file them electronically. The count aggregates all information return types, including W-2s, so a business with eight employees and three contractors is already over the line. That makes paper filing a thing of the past for most businesses with a payroll.
The IRS also tells filers not to check the VOID box when correcting a paper form, since it tells scanning equipment to ignore the entry. When you need to fix a mistake, follow the correction steps in the instructions instead of voiding the original.
Backup withholding: the trap that ignores the threshold
If a contractor does not give you a valid taxpayer identification number, or the IRS notifies you that the number is wrong, you may be required to withhold federal income tax from payments to that person. When you do, you must file a 1099-NEC for that payee regardless of the dollar amount. A $300 payment with withholding still produces a form.
The simplest protection is a W-9 on file before the first payment. A contractor who will not provide one is a risk you should discuss with your CPA before the invoice is paid, not after.
Set up your records now so January is easy
Most 1099 problems are bookkeeping problems. A good setup takes an afternoon:
- Create a vendor record for every contractor with W-9 details, legal name and mailing address.
- Tag contractor payments by vendor and by type: services, rent, reimbursed expenses and product purchases belong in different categories.
- Update the threshold in your software to $2,000 for 2026 payments, and check that any “1099 eligible” flags are still correct.
- Run a mid-year and a December report of everyone near or over $2,000, so you are not surprised.
- Keep personal and business spending separate. The IRS limits reporting to business payments, and mixing the two is a common audit trigger. If you invest on the side, keep those records apart too; year-end tax recordkeeping for investors follows the same principle of organizing records well before filing season.
If your books are behind, fix them before you try to produce 1099s. Our guides on keeping LLC bookkeeping IRS-ready and on the bookkeeping cleanup process cover how to get there, and the small business bookkeeping guide shows what a clean monthly routine looks like. Spanish-speaking owners can also read our guide on formularios 1099 en 2026.
Our perspective: the threshold is not a reason to stop tracking
When a threshold goes up, some owners hear “I no longer have to keep track of contractor payments.” We see it differently. The reporting line moved, but the underlying duties did not. You still need a W-9, you still need to know who you paid and why, and you still need to classify workers correctly.
The owners we work with in Dallas-Fort Worth are usually running a restaurant, a construction firm, a property portfolio, a clinic or a nonprofit, and most use a mix of employees and contractors. For them the real risk is rarely the $600 versus $2,000 question. It is a contractor paid across three different accounts, an invoice coded as repairs that was really a service, or a December payment that pushes a vendor over the line and nobody notices until February.
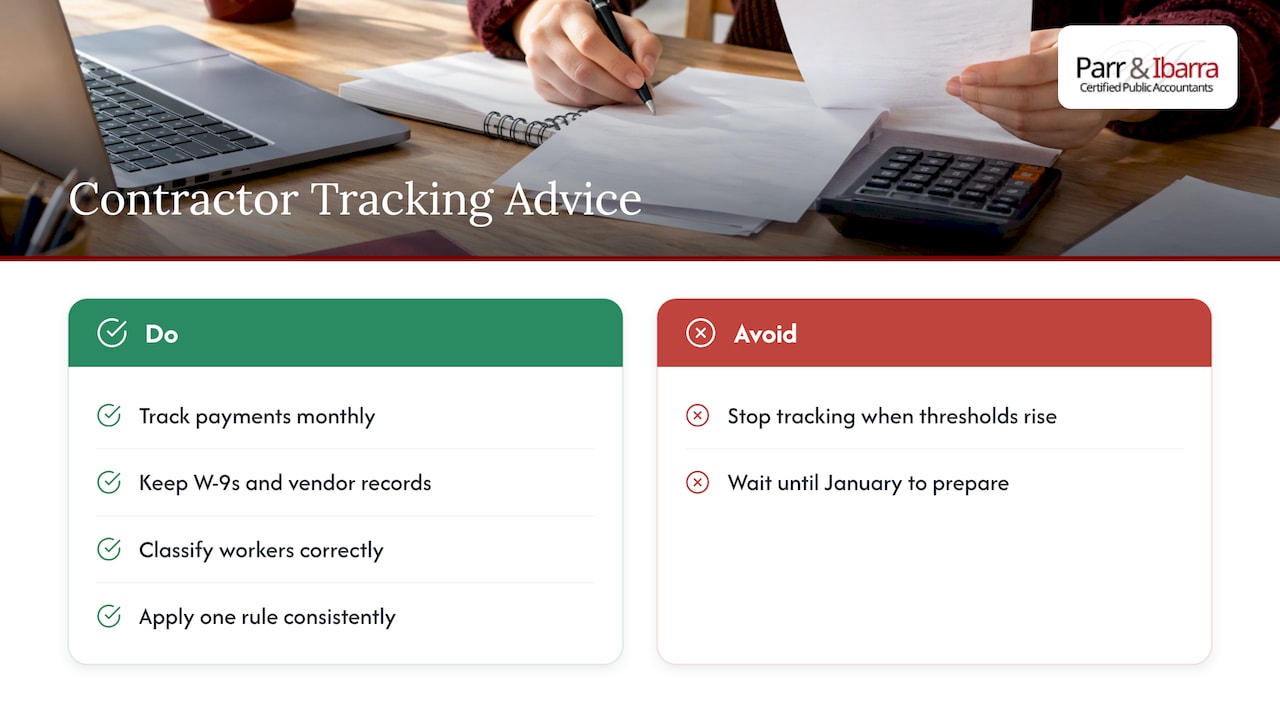
Our advice is to treat 1099 prep as a monthly bookkeeping task, not a January project. A clean vendor file also helps with deductions: if you can show who was paid, for what and when, you are better placed to defend the expense. Our guide to avoiding IRS add-backs goes deeper on that.
And decide deliberately whether to issue forms below $2,000. Some clients prefer to keep one rule for every contractor, because it makes the process simpler, and the IRS allows that. Others follow the threshold strictly. Either works if you apply it consistently and your records are clean.
— Adan
When to bring in a CPA
You can handle a handful of contractors yourself. It is worth getting a CPA involved when:
- you have a mix of employees, contractors and rental or royalty payments and are not sure which form each belongs on;
- you have received a notice about a missing or incorrect TIN, or you have a backup withholding situation;
- you have missed a filing, need to correct forms already filed, or received an IRS penalty notice;
- you are a nonprofit or real estate investor with many vendors and tight reporting needs.
At Parr & Ibarra CPA we handle bookkeeping and accounts payable, payroll and tax preparation and planning for individuals and businesses across Dallas-Fort Worth, with services available in English and Spanish. If you want your contractor payments tracked all year and your 1099s ready before the deadline, contact our team and we will look at your setup.
FAQ
What is the 1099-NEC threshold for 2026?
For payments made in 2026, you generally file a 1099-NEC when you pay a contractor $2,000 or more for services during the year. The prior threshold of $600 applied to 2025 and earlier payments. The $2,000 figure is indexed for inflation starting in 2027.
Do I need to file a 1099-NEC if I paid a contractor less than $2,000?
Usually no, with one major exception: if you withheld any federal income tax from the payee, you must file regardless of the amount. You may also choose to file for smaller amounts if that makes your process simpler.
When is the 1099-NEC due for 2026?
January 31, 2027, for both the IRS copy and the recipient copy, on paper or electronic. Since that day is a Sunday, the next business day, February 1, 2027, is treated as timely.
Is a 1099-NEC the same as a 1099-MISC?
No. The 1099-NEC reports payments for services by non-employees. The 1099-MISC covers other items, such as rents and royalties, and has later filing dates of February 28 on paper and March 31 electronically.
Do I have to e-file my 1099s?
If you file 10 or more information returns in total, including W-2s, you must e-file them. With fewer than 10, paper is still allowed, but electronic filing is usually faster and easier to correct.
Sources
- Instructions for Forms 1099-MISC and 1099-NEC, IRS
- About Form 1099-MISC, IRS
- Publication 1099, General Instructions for Certain Information Returns, IRS
- Am I required to file a Form 1099 or other information return?, IRS