100% Bonus Depreciation is Back! What It Means for NNN Lease Investors

The real estate investing world received a special gift on July 4, 2025 wrapped in red white and blue. Congress restored 100% bonus depreciation with the One Big Beautiful Bill (OBBB). This is a game changer for seasoned investors. This may be the most tax-friendly environment in your life for those who are considering making their first investment. It does more than just reduce your tax bill. This reshapes long-term wealth strategies for NNN (triple-net) lease investors who depend on predictable tax benefits and steady cash flow to maximize returns. This development, combined with the preserved 1031 exchange rules and newly enhanced deductions for business, is what many call the biggest tax victory in recent history for real estate investors. Let’s break down what it means to you, why it is important for NNN leases buyers, and how to strategically position yourself so that you can take advantage of this once-in-a generation opportunity. With 100% bonus depreciation back, it’s the perfect time to understand how it works with cost segregation—start with our complete Guide to Cost Segregation. What is Bonus Depreciation? Why does it matter? Real estate investing has always relied on depreciation. Commercial properties are depreciated according to standard rules over 39 years. This means that you can recover a small portion of your investment every year via tax deductions. It’s an effective benefit, but it is slow to materialize. Bonus depreciation speeds up this process. Investors can deduct a significant portion of the eligible property costs, or in this case 100%, in their first year. This means that investors will receive immediate tax relief and a reduced taxable income. They can also use the savings to make additional investments. Many feared that the tax benefit had peaked when bonus depreciation gradually decreased after 2022. The OBBB, however, has permanently altered the landscape. Congress, by securing 100% bonus depreciation for investors to write off significant portions of property related improvements and components in the future without having to wait decades before realizing benefits. Why NNN Lease Investors Benefit the Most NNN leases are an investment segment that is unique in the world of commercial real estate. Investors can expect a steady, long-term cash flow from these properties. They are often leased out to national tenants with good credit, such as retail chains, pharmacies or convenience stores. Tenants take care of property expenses such as taxes, insurance and maintenance. This allows investors to enjoy passive income, without the hassles associated with traditional rental properties. NNN investment is even more attractive with the restoration of the 100% bonus depreciation. Here’s why: This is especially important for first-time NNN purchasers. You get a steady, hands-off stream of income, and you benefit from a tax incentive that dramatically increases the profitability of your investment. NNN lease investors can significantly accelerate tax savings by combining bonus depreciation with cost segregation, learn how in our in-depth Guide to Cost Segregation. A Perfect Match with 1031 Exchanges The OBBB did not just restore bonus depreciation, it also preserved the much-loved 1031 exchange. These two provisions work together to create an incredible synergy in wealth creation. You can defer capital gains tax by selling an investment property, and then rolling the proceeds into another property of similar kind with a 1031 exchange. You can defer taxes and also get a 100% bonus on depreciation by combining the two while also front-loading enormous depreciation benefits on your replacement property. Imagine upgrading from a small retail property to a big-box NNN-leased store via a 1031 exchange. You can avoid capital gains taxes on the sale and write off a large portion of the value of your new property in the first year. It is very rare to find such a compounding of tax efficiency. This makes the current environment one of best in history for repositioning or scaling your real estate portfolio. Retirement Planning and Generational Wealth NNN properties can be a cornerstone of retirement and wealth strategies for many investors. Renting a property to a national tenant for 15-20 years can provide a stable and predictable income stream that can be used as an asset in retirement or as a legacy. These investments offer an immediate tax shelter, thanks to the 100% bonus depreciation. These investments are particularly appealing to those who are approaching retirement and want to reduce their taxable income during the years of highest earnings while also securing a long-term, reliable passive income. NNN investments are a powerful tool for families who plan to transfer wealth between generations. They can combine tax deferral (1031 Exchanges), tax acceleration strategies (bonus depreciation), as well as estate planning strategies. You can secure these benefits now and not only benefit from current returns, but also protect your heirs financial future. Why 2025 is the Year to Act This advantage of 100% depreciation will not disappear because it is permanent under OBBB. Act now while tax incentives and market conditions are aligned to maximize the opportunity. Commercial real estate is experiencing a unique moment. Interest rates, tenants’ demand and the broader economic climate have all created challenges and opportunities. Investors with a longer-term perspective will find that 2025 is the best time to invest in assets. This is because of the combination of quality tenants, predictable leases and powerful tax instruments. Our team is specialized in helping first-time NNN Lease buyers find the best property to meet their budget, income requirements, and investment goals. We do more than just find you a property. We guide you through every step of the process from due diligence, to tax strategies, to long-term planning. Expert guidance to navigate Through the complexity The real estate market and tax code can be complex, but the potential rewards are great. Each investor has a unique situation, so structuring the purchase to maximize benefits requires careful analysis. Not all components of a property are eligible for bonus depreciation. To determine which parts of the building or improvements can be expedited, a cost segregation study may be
Leveraging Bonus Depreciation and Cost Segregation Post-Trump Tax Reform
On July 4, 2025 President Trump approved the 2025 tax reform into law, known as H.R. 1. Republicans’ “One Big Beautiful Bill.” One of the most important provisions is the permanent reinstatement of 100% bonus depreciation, providing a long term clarity for capital investment and tax planning strategies. Key Takeaway H.R. 1, largely shaped by the Senate’s provisions to guarantee bonus depreciation is a significant win for taxpayers who are planning major investment projects, or real estate investment. By ensuring the 100% bonus depreciation rate by raising section 179 thresholds, adding the full deduction of certain commercial buildings, as well as establishing an explicit timeframe to end section 179D, this drastically changes the tax strategies for 2025 and beyond. To better understand how bonus depreciation works alongside cost segregation, start with our complete Guide to Cost Segregation and its tax-saving benefits. Trump Tax Bill Bonus Depreciation Changes The Senate version of the bill, ultimately approved through the House and subsequently signed by President Trump, marks an important change by adding a 100% depreciation bonus provision for qualified property placed into service after the 19th of January 2025. This effectively eliminates the phase-down which was set in the Tax Cuts and Jobs Act (TCJA) of 2017. In the initial TCJA, bonus depreciation was fixed at 100% from 2022. It was then set to drop by 20% per year. In 2025, companies faced only a 40% write-off in the first year, with a complete phase-out on the horizon. The Senate-driven clause of the bill reversed that trend by restoring the full incentive for indefinitely. Explore our complete tax planning guide to learn how real estate, business structure, and income planning work together to maximize long-term tax efficiency. Impact on Cost Segregation Studies Cost segregation studies are a tax-efficient strategy that allows taxpayers to accelerate depreciation deductions on real estate investments. The study breaks down the cost of a building into parts which can be depreciated over shorter periods of recovery (typically 5, 7, or 15 months) rather than the typical 27.539-year or 27.5 or 39-year timeframes. This shifts the majority of investments into categories that qualify for acceleration depreciation, which increases tax deductions for early years and enhances cash flow. Why a Cost Segregation Study Is Now More Valuable With the bill’s permanent 100% bonus depreciation, each dollar converted into short-life modified accelerated cost recovery systems (MACRS) property as a result of cost segregation studies can be deducted fully within the first year. This allows for large upfront deductions that were in danger of being reduced under the previous law. Enhanced IRC Section 179 Expensing H.R. 1 also increased the IRC Section 179 cap up to $2.5 million, which allows businesses to instantly expense more qualified property. This is particularly beneficial for investments that are smaller, personal property additions and purchases of equipment. In conjunction with cost segregation as well as bonus depreciation, Section 179 is applicable to purchases of smaller assets (up to its limit) and cost segregation grants more deductions, accelerating the depreciation of structural components that is eligible for 100% bonus treatment. New 100% Depreciation for Certain Qualified Production Property Another notable aspect of the tax reforms is the inclusion of a new 100% first-year depreciation deduction for commercial real estate that is used for the production of qualified production activities. Qualified production properties (QPP) can be defined as a component of nonresidential real estate used by the taxpayer as an integral component of a production activity that is qualified. In keeping with the overall goal of reshoring production towards the United States, QPP must be able to meet a number of requirements, including: This rule is anticipated to be beneficial to manufacturing and production businesses planning to build or improve manufacturing facilities across the United States by allowing the taxpayer to deduct all construction costs within the first year. While this law provides significant advantages, it’s also targeted only taxpayers who meet all qualified production activity criteria are eligible. Businesses that could be eligible are those that produce goods, operating industrial facilities or manufacturing components as well as final products. An in-depth analysis of the project’s scope as well as timing and usage is vital to determine whether a company is eligible for this significant first-year deduction. Bonus depreciation and cost segregation became significantly more powerful after the Trump-era tax reforms, allowing real estate investors to accelerate deductions and reduce taxable income early in the investment lifecycle. When applied strategically, these tools are a key part of a broader real estate tax strategy for maximizing depreciation benefits, helping investors improve cash flow and reinvest more efficiently. Tax Planning Implications for 2025 and Beyond It is essential to plan ahead in 2025, when the tax reform will create a new and exciting landscape for real estate owners as well as businesses: Dive into our comprehensive tax planning guide to discover advanced strategies for reducing taxes, improving cash flow, and building long-term wealth through smarter structuring. Want to maximize your tax savings under current tax laws? Explore our full Guide to Cost Segregation to see how to combine these strategies effectively. Next Steps To Guide You Forward To get the most value from the tax reform provisions of 2025, businesses should begin planning in advance to be ready for important deadlines and maximize available incentives: Related Posts Guide to Real Estate Tax Strategy
How the 2025 Reconciliation Bill Reshapes Tech Taxation
On the 4th July of 2025 the president Donald Trump signed P.L. 119-21, also known by the name of “One Big Beautiful Bill Act” into law. The bill’s provisions affect technology companies through reinstatement of bonus depreciation, restructuring research and experimental (R&E) incentives and changes to Section 1202 qualified small-business stock (QSBS) rules, and the amendment of international tax regulations. Explore more deeply the details of the 2025 final budget reconciliation bill using our in-depth analysis. Key Tax Provisions Impacting Tech 1. Full Expensing for Infrastructure and Capital Investments The bonus depreciation rate of 100% is now available to qualified properties that are placed in service after January 19th 2025. Companies can immediately deduct the entire amount of capital investment eligible which include servers, network equipment, laboratory instruments, and tools for software development. For companies that are scaling AI (AI) infrastructure, semiconductor fabrication, as well as cloud-based computing platforms, this option can significantly increase the ROI of capital-intensive initiatives. It also promotes earlier investments in the next generation of technologies through reducing initial taxes. 2. R&E Capitalization Relief The bill repeals the rule of 2022 which required companies to amortize section 174 R&E costs over five years. In 2025, companies can once again fully deduct these expenditures in the year they are incurred. This can be particularly beneficial to tech companies involved in areas in which R&E costs can be very high or are frequently incurred, such as: The immediate reduction of domestic R&E expenditure improves cash flow, and also reduces taxable income, allowing funds to invest in new ideas. Furthermore, companies can increase the domestic unamortized R&E costs until 2025 or spread them across two years, based on their strategic requirements. It is vital to keep in mind that taxpayers are still required to amortize and capitalize foreign R&E expenses over a period of 15 years. 3. Retroactive R&E Deductions for Small Businesses Small businesses that are eligible, that is, those that have smaller than $31 million in annual gross revenue for the three prior tax years, the bill permits retroactive deductions for domestic R&E expenditures beginning in the tax year 2022 until 2024. This presents a unique opportunity to amend tax returns for prior years to claim refunds of tax payments already made. It is important to remember that this is an option on the return, and for which currently there is no guidance and accounting method change. Our advisory services will help you navigate the maze of determining eligibility, filing amending return, accounting technique adjustments and also coordinating to Internal Revenue Code (IRC) Section 280C in order to maximize the potential benefits. There are many aspects to be taken into consideration in deciding whether to use the retroactive option. The nature of the entity is going to determine the complexity of the evaluation. 4. QSBS/Section 1202: A New Landscape for Startup Investment The tax reform of 2025 makes significant modifications to section 1202 of the IRC that governs the tax treatment for qualified small-business stock (QSBS). In the past, Section 1202 allowed investors to exclude up to 100% of the capital gains (depending on the date of acquisition) when selling QSBS that were held for longer than five years. This is an incentive that was crucial in driving early-stage investment in technology startups. For QSBS stocks that was acquired after July 4 2025, there’s a tiered structure for the gain exclusion based on the length of time the stock was held: Investors can receive certain exclusion benefits so provided that the shares eligible for exclusion are held for a minimum of three years. This may alter the calculation of return on investment and the speed at which founders and investors are able to begin selling their shares while still receiving good benefits. Two other changes cover the total gain exclusion and the gross asset limitations for shares acquired after July 4, 2025, including: These adjustments only apply to shares that were issued after July 4, 2025. The provisions permit investors to enjoy a greater limit on the amount they can earn. They also raise the maximum amount of gross assets and, as a result, growing companies or those that grow too big may be allowed to issue QSBS yet again. There are also planning opportunities associated with the change to the retroactive election to deduct the capitalized R&E amounts that could make companies fall back under the $50million cap in 2022 – 2024. 5. International Tax Adjustments: GILTI & FDII The law also brings important changes to two tax rules that apply internationally: GILTI (Global Intangible Low-Taxed Income) A new title, “Net CFC Tested Income” (NCTI) will reflect the shift in taxation that currently applies to foreign intangible income, to creating the global minimum tax. The reduction in the deduction from 50% to 40% and the removal from the qualifying business asset investment (QBAI) reduction is expected to boost the offshore earnings of technology companies which are subject to U.S. tax. However, more specific modifications to the cost of foreign tax credit allocation rules could result in a positive net outcome for companies in the field of technology. Therefore, it is recommended that technology companies consider what changes to the system that take effect in 2026 will affect their particular tax situation, since the effect of NCTI is not identical across all companies. FDII (Foreign-Derived Intangible Income) FDII is changed to foreign derived deduction eligible income (FDDEI) in the shift away from focusing on the export of intangible sources and expanding the scope of benefits to include firms with more tangible assets. Although the total deduction has been decreased from 37.5% to 33.34%, a lot of companies will nonetheless reap larger gains due to the elimination of QBAI reduction and decrease of certain expenses apportioned against FDDEI, which formerly reduced the benefit. Technology-related companies need to examine what the changes to FDDEI rules will affect their specific circumstances and plans according to the new regime. International tax regulations are complex and have been changed drastically. It
Understanding the Differences Between Form W-2 and Form W-9
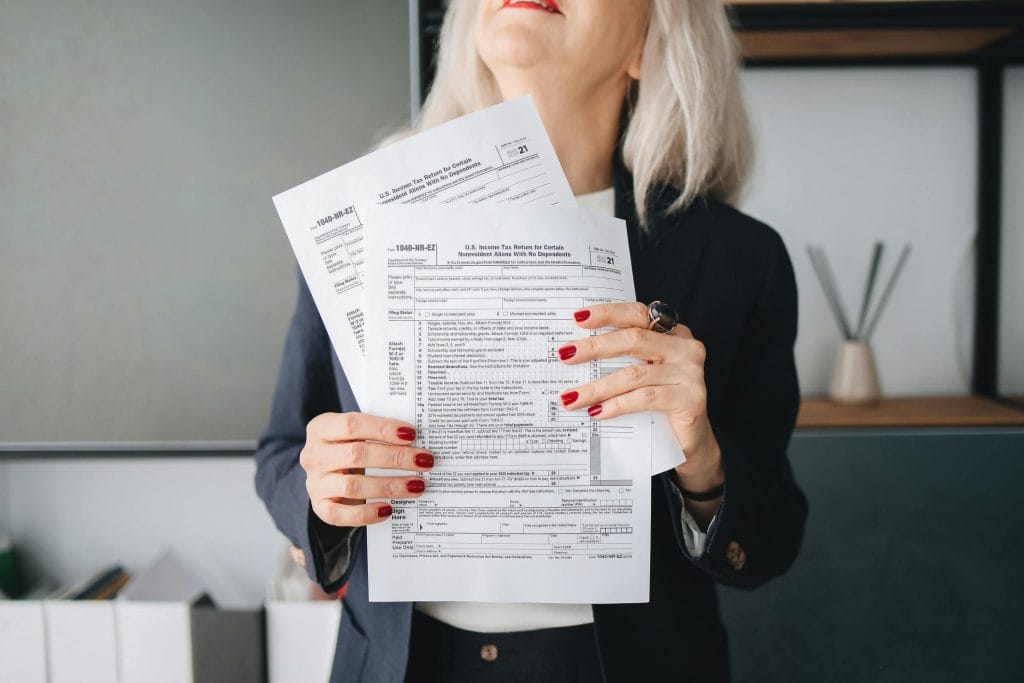
Employers and employees can get confused by the complex tax system in the United States. There are two tiers of taxation in this country , federal, and state. The calculations for each are different. The tax calculations are also different for each state, which adds to the confusion. The different tax forms that are required for workers, depending on their employment relationship with an organization, adds another layer of complexity. The Form W-9 and the Form W-2 are two forms that look similar but are very different. This article will compare Form W-2 and Form W-9, as well as their tax implications to help you decide which one you should file. Understanding Forms W-2 and W-9 The employee’s contract with their employer will determine the tax forms and process. The appropriate tax forms must be filed for employees based on these factors. What is Form W-2? In the U.S., every employer has tax obligations. This includes creating tax forms. This includes Form W-2. The employer generates this form and sends it to the employee by January 31st. This form contains information about the amount of income tax withheld from an employee’s paycheck. This form also contains information about other payroll taxes withheld, such as Social Security Tax or Medicare. This form is used by employees to prepare and file their federal income tax returns before the April 15th deadline. Only employees on the payroll are eligible to receive this form. Before generating the form W-2, employees must submit a W-4 form that contains taxation information, their filing status and if they have multiple jobs. The employer calculates the tax that will be deducted from each paycheck based on the information provided in Form W-4. The Form W-2 will show the taxes that were taken out. What is Form W-9? This form is used by freelancers, independent contractors, and self-employed people who offer services to companies. These contractors do not work for the company. Independent contractors are required to provide their employer with information using this form. This includes their name, social security number/taxpayer identification number, and address. The organization that hires these contractors will use this information to prepare a1099 form for tax filing. In this case, the organization does not deduct any money from the contractor’s income. The contractor is responsible for reporting and paying taxes. The Differences between Form W-2 and W-9 Although both forms are used to collect tax, they differ in their contents, purpose and filing process. Here are some of the main differences between W-2 and W-9. Who uses each form? The employer is required to send the employee Form W-2. This form contains information on the amount of income tax withheld by the employer from an employee’s pay. This form is used by employees to submit their income tax. The Form W-9, on the other hand, is filled out by independent contractors, freelancers, or self-employed individuals and sent to organizations to which they have rendered services. This form contains information about the contractor, such as his name, address and SSN/TIN. Tax Withholding and Payroll Deductions The tax withheld is one of the major reasons why there are different forms. Employers are required to withhold certain amounts of income tax on each employee’s paycheck. They must also withhold Medicare and Social Security taxes in addition to the income tax. The Form W-2 contains all the details of these taxes. The organization that hires W-9 contractors is not responsible for their tax payments, and will not collect any taxes. The contractor is responsible for submitting a W-9 to the organization which they work for. The IRS allows the employer to deduct 24% from the contractor’s income if the W-9 is not provided. Reporting Income to IRS Employers must report Form W-2 to the IRS along with generating it. The original copy must be sent to employees, and a digital version or a copy should be sent to the IRS. When the employee files their taxes, the IRS will check the W-2s sent by the employer to ensure accuracy. The $600 threshold only applies to the 1099-NEC form that is used to report payments. Contractors should complete and submit the W-9 form before beginning any service, regardless of income. Choosing between a W-2 employee and a W-9 contractor affects payroll taxes and compliance obligations. Explore our Texas payroll compliance guide to better understand worker classification, payroll reporting, and employer tax responsibilities. Impact on Social Security, Medicare W-2 forms are issued to employees who are on the payroll of the employer. The employer pays a portion of the employee’s Social Security and Medicare tax. They are therefore less burdened. Independent contractors, on the other hand, are responsible for paying all Medicare and Social Security tax. It can result in a higher tax burden for them. Thus, these are the W-2 vs. W-9 tax differences. What is the difference between an employee and an independent contractor? You now know the various forms and when to generate them. Should you be an independent contractor or employee? Consider these aspects: Employer Control vs. Worker Independence The level of control the employer has on each individual’s daily activities is the main difference between being an employee and working as an independent contractor. Employers have total control over their employees’ work. They must adhere to a schedule and perform assigned tasks. In certain cases, the employee is required to work exclusively for their employer during a specified period. An independent contractor, on the other hand, has greater flexibility. They are not under the employer’s control and do not always need to adhere to a set schedule, as long as their agreed upon responsibilities are met. Benefits and Protection Employees receive many benefits and protections in exchange for the complete control of their employer. Employers pay for health care, pension contributions, Medicare, Social Security, and contributions to 401(k)s or other pension funds. This reduces employee financial burden. Contractors are not eligible for any of these benefits. They must pay their own healthcare premiums,
S-Corp Tax Benefits for Real Estate Agents
Real estate agents can choose a structure that best suits their professional and financial objectives. According to research, the two most common business structures used by real estate professionals are S-Corps and LLCs. Both offer greater tax benefits than a C-Corp or sole proprietorship. S-corps are better than LLCs from a tax perspective. They offer more benefits, legal protection and increase your reputation with clients. Take a closer look at the five top tax benefits that an S-Corp can provide for real estate agents. 1. Reduce Self-Employment Taxes It’s crucial to keep track of self-employment taxes, as they can add up quickly. All net income of LLCs is subject to a 15.3% SE Tax Real estate agents who are registered as LLCs or sole proprietorships must pay self-employment taxes at a rate of 15.3%. 12.4% of this tax goes to Social Security, and the rest 2.9% to Medicare. S-Corps allows splitting income: Salary vs. Distribution You can divide your income in two when you convert to S-corp. One part is a salary, and a distribution to shareholders. The first part of the income is taxed but not the second. The entire salary portion is subject to payroll taxes, including social security and medicare. S-Corps are only advantageous if you are able to save money by setting the “reasonable salary”. At the same time, the IRS has set certain rules for the salary. Real estate agents who earn $75,000+ can save up to $10,000 per year. Assume you’re a real estate agent who follows a sole proprietorship and earns more than $75,000. You will be charged a 15.3% self-employment tax, which is $11,475. You will also be required to pay federal and state income tax. When you switch your company to an S-Corp structure, you can choose to split the income as salary and distribution. There are also no self-employment taxes as you will be considered an employee. You can save anywhere from $5000 to $10,000 in taxes per year due to these factors. 2. Pay Yourself a “Reasonable Salary” + Take Tax-Free Distributions You are both an owner and an employee when your company is an S-corp. You can choose how to divide your income. Note that the IRS requires that S-Corps owners be paid a reasonable salary. Payroll tax is only applicable to the salary portion Many agents pay themselves a nominal or reasonable salary. This salary is subjected to payroll taxes including social security and medicare. Make sure your salary is equal to or higher than the minimum wage in your state. FICA tax is not applicable to distributions After paying a reasonable salary, you can take the rest as a distribution, which is not subject to FICA taxes. This means you get a certain amount as tax-free income. You can decide how much goes to profit vs. salary This arrangement offers you a lot of flexibility and allows you to keep more income. You can decide to distribute more money while maintaining the minimum wage rate. This requires financial planning, and an understanding of the tax laws in order to be compliant and avoid IRS audits. Parr & Ibarra CPA will help you determine the best balance based on the amount of money that you earn and the tax rates in your state and federal jurisdiction. 3. Claim More Deductible Business Expenses Switching to an S-corp also allows you to claim your business expenses as income. These deductions, however, must be documented in compliance with IRS guidelines. Payroll processing fees, health insurance and retirement plans Deductions for organization-related costs include employer-paid health insurance premiums, 401(k) contributions and payroll services. These deductions reduce your taxable income. Business use of home, marketing tools and vehicle mileage You can also deduct costs for your home office. These include vehicle mileage for client meetings, showings and listing fees, cost incurred for marketing and other expenses related to running your business. These expenses can all help you reduce your taxable income. Parr & Ibarra CPA identifies industry-specific deductions You can also take advantage of many deductions that are specific to your industry. Signage, staging costs, continuing education for improving your real estate business and MLS fees are some examples. Our experts will review your expenses and costs to determine if you are eligible for any deductions. 4. Take Advantage Of The QBI Deduction You can take advantage of many tax benefits as an S-Corp. Here are some of the most important. Tax deductions up to 20% on Qualified Business Income(QBI) The IRS allows individuals to deduct something called qualified business income (QBI). Also known as the section 199A deduction. QBI allows you to deduct up to 20% of your taxable income. However, you must meet certain criteria in order to claim this deduction. Available to S-Corp owners under certain income limits QBI can only be claimed if your income is below certain limits. The limits for 2025 are $197,300 if you file a single return and $394,600 if you file a joint tax return with your spouse. Payroll balance and entity structure are important. To qualify for these deductions, your S-corp needs to be set up according to the current laws and your salary must be reasonable. We will help you structure your S-corp to meet the QBI requirements so that you can receive a 20% tax deduction. 5. Improve Your Business Credit Rating And Appear More Professional Switching to S-Corp is more than just taxation. S-Corp status increases credibility among lenders and investors S-corps are more professional and show continuity of business when compared with sole proprietorships or partnerships. It reflects professionalism when you have your own bank account. This builds trust and credibility with customers. Separate your business finances from personal finances A S-corp also requires a separate bank account and a simplified payroll setup. Both of these add to the financial stability. You can then attract more customers, and also qualify for lines of credit and business loans. Your real estate business is easier to hire, sell, and
Paying Taxes on Reinvested Dividends? Optimize Your DRIP Strategy
Dividend reinvestment plans (DRIP) are often used by investors to automatically compound their investment returns. Before you think it’s obvious, ask yourself if reinvested dividends are taxable?. Your after-tax returns can be significantly affected by the answer. Reinvesting each dividend can reduce your liquidity and increase concentration risks. Know what to lean in (or out). Understanding dividend reinvestment plans When you receive a payout, you have two choices: either take it in cash or reinvest. Dividends are usually paid directly to investors if not participating in active DRIPs. DRIPs are a way to reinvest dividends in the purchase of additional shares. Reinvestment takes place on the date of dividend payment, be it monthly, quarterly or semi-annually. The market value of the investment determines how many shares are acquired. Taxation of dividends reinvested Dividends are not all treated the same. To maximize your DRIPs, you need to understand the difference between ordinary and qualified dividends. U.S. companies or qualified foreign entities pay qualified dividends. These dividends must be held over a certain period of time to qualify for favorable treatment. You may be eligible for long-term gains tax rates of 0%, 15% or 20% depending on your income bracket. Ordinary dividends will be taxed according to your normal income rate. Knowing whether you have ordinary or qualified dividends can help you to forecast your tax situation since reinvested dividends are subject to taxation in brokerage accounts What happens if you reinvest your dividends? Imagine you own 100 shares in a company which pays a dividend of $1.00 per share quarterly. Without reinvesting your dividends, you would receive $100 each quarter. Enrolling in DRIPs allows you to automatically buy more shares with that $100. If the stock is trading at $50 per share then your $100 dividend will buy you additional shares. You now own 102 shares. If the dividend payment is not exactly in line with the price of the stock, you can still purchase fractional shares as DRIPs often accommodate fractional shares. When to reinvest dividends and when to take cash instead Reinvesting dividends is a great way to compound wealth. This is especially true in tax-advantaged account types such as IRAs or 401(k), where dividends reinvested are not taxed. Reinvesting dividends can be a powerful tool for compounding wealth. If your portfolio is well-diversified with broad-based ETFs or mutual funds, reinvesting can help maintain steady growth. If you have a concentrated position in stocks, taking the dividends as cash could be the best option. Reinvesting would increase your exposure to risk specific to the company. Dividends paid in cash give you the option to diversify your portfolio by reinvesting into other investments. Portfolio imbalance: a hidden risk with DRIPs DRIPs are a great way to simplify your investing. However, they can also expose you to more stocks. This can cause portfolio imbalance, especially if you automatically reinvest a large portion of your portfolio into one stock. DRIPs can overload your portfolio if they are concentrated in a single sector or stock. Reallocate dividends into other investments rather than reinvesting them in the same security. Reinvesting dividends automatically might seem the best move, but does it serve your larger financial picture? You can take control of your finances by creating a tailored dividend strategy. This will help your money to work towards your goals, rather than blindly following defaults. Conclusion Dividend Reinvestment Plans (DRIPs) provide investors with the chance to slowly build wealth by putting dividends to work in a way that is automatic. Instead of cash payouts and reinvesting the dividends, they help create a greater share of the market, and compounding dividends over time, without the stress of trading. No matter if you’re an experienced investor looking to build your portfolio over time or an aspiring investor looking for a more disciplined approach in investing, DRIPs offer an accessible cost-effective strategy to boost your portfolio. We at Parr & Ibarra CPA in Keller, Texas believe in helping investors develop financial strategies that match their long-term objectives. If you’re looking to learn the ways DRIPs as well as other investments can aid in your financial goals, our team is ready to help you through every step of the process.
7 Strategies to Reduce Capital Gains Tax on Real Estate
Selling a property after you have built up wealth in real estate can be a double-edged blade. You’re releasing capital to pursue new opportunities. Capital gains tax on the sale of real estate can be a huge drain on your profits. Federally, it could reach 37%. Many states also impose a capital gains tax. The good news? When selling real estate, there are tax-efficient and legal strategies that can help you manage your tax bill. Here are seven ways to manage taxes when disposing of real estate, whether you want to reinvest in your portfolio, simplify it, or move into a more passive income. Reducing capital gains tax on real estate requires proactive planning, including strategies like 1031 exchanges, timing of sales, and leveraging depreciation recapture rules. When these approaches are integrated into a broader real estate tax strategy for minimizing capital gains liability, investors can preserve more equity and improve long-term portfolio growth. Explore our complete tax planning guide to learn how to combine property strategies, income timing, and investment planning to minimize your overall tax burden. 1. 1031 Exchange It allows you to sell one property and reinvest the proceeds into another property of “like-kind” while deferring taxes on capital gains. This strategy is especially useful for investors who want to upgrade their properties, move to a new market, or consolidate a portfolio without having to pay immediate taxes. To qualify, however, there are strict IRS rules. You must, for example, identify a new property within 45-days and complete the purchase in 180-days. Here’s a hypothetical case. An investor wants to sell an apartment building originally purchased for $750k but now valued at $2M. The investor exchanges it for a commercial property worth $3M using a 1031 exchange, deferring the capital gains tax of $1.25M. 2. Delaware Statutory Trusts (DST) Investors may decide that they do not want to manage the real estate, but still have gains embedded for a long time. In this situation, a Delaware Statutory Trust can be used. DSTs are a way for investors to pool their resources to invest in institutional-grade real estate such as multifamily properties, office buildings and medical centers, without having to worry about the operational duties of ownership. A DST qualifies as a 1031 Exchange Replacement Property, which means you can sell your property and reinvest in a DST. DSTs also provide passive income via rental distributions. This is a great alternative for investors that prefer to invest in real estate without having to be hands-on. Here is an example. An investor retires and sells his rental property to reinvest in a DST. He gains a steady income, while eliminating the management responsibilities. This allows for an easy transition from active ownership of real estate to a passive approach, reducing the day-to-day stress of property management or oversight. Looking to reduce your real estate tax burden? Start with our complete Guide to Cost Segregation to explore strategies that can complement capital gains tax planning. 3. The Qualified Opportunity Zone (QOZ) Fund Investors are offered a powerful incentive by Qualified Opportunity Zones. They can defer capital gains tax until December 31, 2026 by reinvesting the gains in a QOZ Fund. If the investment is held at least for 10 years, the gains from the QOZ investment could be tax-free. The law does provide this treatment but it is not automatic. Investors are required to meet strict eligibility requirements, adhere to strict timing requirements and make sure that the investment is compliant with ongoing program rules. Plus, the long-term benefits are subject to the continuation of the QOZ program itself While QOZs are a powerful planning tool, it is important to fully understand their requirements and not just focus on the headline tax benefits. The funds aim to stimulate economic development within designated Opportunity Zones and offer significant tax benefits to investors who are willing to hold their assets for a long time. This is an example. In June 2025, a business owner sells his company and invests the $5M in gains back into a QOZ Fund. Taxes on these gains can be deferred until 31 December, 2026. If they stay invested until June 2035, taxes will not be due on the appreciation. This strategy is especially attractive to investors who want to diversify their investments into development projects and promote tax efficiency. Dive into our comprehensive tax planning guide to discover smarter strategies for deferring taxes, preserving profits, and building long-term wealth. 4. Charitable Remainder Trust (CRT) If you’re philanthropically inclined, a Charitable Remainder Trust (CRT) allows you to donate real estate or other appreciated assets, avoid capital gains taxes, and receive income for a specified period of time. A CRT allows the donor to transfer property into the trust and then sell it tax-free. Receives income from its investments. The remaining assets are given to a charity upon the death of the donor or the expiration of the trust. 5. Seller financing (installment sales) Instead of selling your real estate investment in a lump-sum (and the tax bill that comes with it), you can spread out taxable gains across several years and reduce your tax burden. Sellers can avoid a capital gains tax by structuring their sale as a long term agreement. An example. The seller financed the sale of a $3M rental property over 10 years. This reduces their annual taxable income, while they collect principal and interest from the loan. This method is particularly helpful for those who want to reduce their tax liability while maintaining a steady cashflow for several years. 6. Estate planning and gifting Strategic gifting is a way to transfer wealth and avoid estate or capital gains taxes if your real estate portfolio forms part of your legacy. You can pass your real estate assets to your heirs in a tax-efficient manner by using tools such as Trusts, Family Limited Partnerships (FLPs) and Grantor Retained Annuity Trusts(GRATs). Well-planned estate transfers can help reduce taxes and keep assets in the family. According to
Pre-IPO Strategy: How to Get IPO-Ready
If you have worked for a public company before, you are familiar with the quarterly earnings cycle and employee benefit structure. But preparing for your own company’s IPO is something new. Pre-IPO planning doesn’t only mean cashing-in. It is about converting years of work into long-term wealth, and aligning that with what matters most. The scenarios we are about to discuss are hypothetical, and they do not reflect actual client experiences. Individual results will vary. What to consider as you prepare financially and strategically for the IPO of your company. Understand what you own — and what it’s worth Take a detailed stock of your equity compensation before your company goes public. Restricted stock units (RSUs) are one example. They vest over a period of time and become ordinary income when they vest. If you have incentive stock options (ISOs), they can offer long-term capital gain treatment, if they are held correctly. However, ISOs may trigger the Alternative Minimum Tax (AMT). Meanwhile, non-qualified stock options (NSOs) are taxed upon exercise and require careful planning to manage their impact. You’ll be faced with a very important question: Should I exercise my options before the IPO, or wait? You’ll need to model ISO scenarios that take into account AMT exposure. This could include early exercise, exercising immediately after the IPO , partially over time or waiting until you meet long-term holding requirements. Understanding your vesting schedules and strike prices, current 409A valuations, and timelines for expiration are all important. These factors will determine when and how you can access liquidity as well as any taxes you may have to pay. Consider a hypothetical scenario. You own 50,000 ISOs that are fully vested. You are considering exercising your ISOs pre-IPO in order to kick-start the long-term gains clock. CPA calculates that exercising now will trigger $300K of AMT exposure. Is it worth it? Should you spread it over two tax years? These are real trade-offs. Plan ahead for tax events Even if you do not sell, an IPO is a taxable event. This is the sneaky part. RSUs trigger income tax at vesting, ISOs can create AMT exposure if exercised before the offering, and selling shares after the IPO leads to capital gains taxes either short-term or long-term, depending on how long you hold them. We often get asked: Will the IPO trigger tax liabilities? In many cases, yes. The vesting of RSUs and the exercise of options, even without the sale of a single share, can generate substantial taxable income. You should model your tax implications with your advisor in advance, as they may differ depending on the timing, equity type and your individual circumstances. QSBS treatment (Qualified small business stock) is another layer of complexity. If you have held eligible stock (before the One Big Beautiful Bill Act’s (OBBBA’s) effective date) for at least five years, or three years (if purchased after that date) and you qualify under Section 1202 of the tax code, you could be able exclude capital gains up to $10 million (or 10x basis) (if purchased before the OBBBA’s effective date) and $15 million (if purchased after the OBBBA’s effective date).However, entity structures like FLPs or pre-IPO gifting can impact eligibility, so your advisor team should discuss these implications early. Keep up with the latest trends by using a tax-model that can accommodate different sales timelines. A good advisor will be able to simulate different “what-if” scenarios, taking into account your tax exposure and diversification goals. Consider two scenarios: One where you sell everything at the IPO, and you face a large tax bill, and another where you hold it for a year or more and benefit from long-term gains rates. Early in the year before RSUs vest you can also discuss with your advisor ways to offset your taxable income by making charitable and retirement contributions. Planning allows you to be flexible and reduces the chance of surprises. Strategize around liquidity and lockup windows You may have shares worth millions of dollars on paper, but this doesn’t mean that you can sell them right away. Insiders are restricted from selling their shares for six months (lock-up period) after an IPO. It’s crucial to have a plan in place for liquidity well before the IPO. It’s a common question: Do I need to create a trust, an LLC, or another entity before the IPO?. It may be advantageous to create a single entity to consolidate or manage your holdings if your goals include estate planning, asset protection, or managing your family ownership structures. What about charitable giving, then? Pre-IPO can be a great time to take action if you are considering establishing a foundation or donor-advised funds (DAFs). However, timing is key. Your gifts must be made prior to any legally binding agreement for sale in order to avoid IRS scrutiny over “pre-arranged sales”. Tax and legal advisors can help you structure your gifts to maximize deductions and minimize IRS scrutiny. Once the lockup period ends, you’ll want a clear plan in place. A Rule 10b5-1 plan allows you to pre-schedule sales while remaining compliant with insider trading laws. It also helps you avoid making emotional, market-timing decisions. Consider a hypothetical scenario. You create your 10b5-1 plans months in advance. Your shares will be sold in three-month increments as the lockup period concludes. This helps you to reduce the impact on your tax situation of the market fluctuations. In a different version of this scenario, knowing that disciplined execution is key, you would resist the temptation to wait for a stock run-up after the lockup period and stick with the plan. Diversify before the window is opened Concentrated stock positions can increase both the upside and downside. If your wealth is largely tied to the equity of your employer, a thoughtful diversification plan is crucial. You could reallocate your investments into broad market funds in order to reduce the risk of being exposed to the performance of a single firm. Consider private investments as a way
Understanding Business Entity Structures and Their Tax Implications
Launching the business of your dreams is an incredible feeling. If you don’t plan your taxes well, this high can quickly become a financial disaster. There are many ways to reduce your tax bill in an ethical and responsible manner! Inside of that many pages of tax complexity leaves a lot of opportunity to reduce your tax bill. Our experience shows that most business owners do not understand their tax plan. Many business owners get confused by the different ways that a business can be managed and structured. To simplify these complexities and understand how tax rules apply across different entities, explore our IRS tax and compliance guide for a broader perspective. In general, the structure of your business will directly impact how much you pay in taxes, how you declare income, which deductions you can claim, and whether you’re exposed to audits or liabilities. Understanding how these rules apply in practice is easier with a reliable IRS filing and tax structure resource that breaks down key requirements for each entity type. A single mistake can have a significant impact on your financial plan if you are managing a large amount of wealth or multiple businesses. Explore our complete tax planning guide to understand how to choose the right entity and build a tax-efficient strategy from day one. This guide will outline the most common business structures, and their tax implications. You can then identify the impact of each structure on legal risk, compliance load, control and, most importantly, your bottom line. Understanding the major types of business structures Each business structure has its own unique mix of administrative, legal and tax considerations. Some offer flexibility and minimal paperwork, while others demand greater compliance for better liability protection and easier access to capital. Sole proprietorship A sole proprietorship is the easiest way to begin a business, but also one of the most risky. Legally, you and your business are legally the same. You report your business income in your personal tax return. However, you are still liable for any business debts or legal issues. The system is easy to manage and set up, but offers no protection for your personal assets in the event of a disaster. Partnership In a partnership, two or more individuals share a business. Profits and losses are passed directly to each partner’s personal tax returns. You will file an informational report to file your overall business activity. In a general partnership, all partners are jointly liable. Limited partnerships (LPs), and limited liability partnership (LLPs), on the other hand, provide an additional layer of protection. LPs separate general partners (who manage and assume liability) from limited ones (who invest). While LLPs protect each partner against the actions of their partners, which is particularly helpful for professional practices such as law or medicine. Want to go beyond the basics of entity selection? Dive into our 2026 Texas Business Tax Guide for deeper insights on compliance, deductions, and strategy. Limited Liability Company (LLC) An LLC combines the ease of pass-through taxes with the legal protection provided by a corporation. Single-member LLCs will be taxed the same as sole proprietorships, and multi-members LLCs as partnerships. The tax treatment of LLCs is either S corporation or C corporation. The LLC is a flexible and widely recognized entity that shields personal assets from the red tape corporations are often subjected to. In some states, however, compliance and fees can be very substantial. Choosing the right tax election requires clarity on reporting and compliance, which you can find in this IRS business tax guide. C-Corp A C corporation is a separate legal entity that pays its own tax and protects you from liability. This is the best option for growth, with stock options, external investors and unlimited shareholders. Double taxation is a downside. The first is the corporate tax, and then the second is the dividend tax. This is the best setup for those who plan to reinvest their profits, raise outside funding or go public. Running a C-corporation comes with additional paperwork and formalities such as board meetings and resolutions. It also requires strict record-keeping. If you want to build a big company, then this is a good option. S-Corp An S-corporation allows you to transfer income, losses, deductions and credits directly to your shareholders. The company does not pay corporate income tax. Instead, it shifts that burden to the shareholders who then report the income flow-through on their personal returns. The C-corporation structure does not allow you to avoid double taxation. The IRS does not give out S-Corp status freely. Your corporation must meet certain requirements to qualify. Even after approval, S corps may be subject to taxes on selected built-in gains and excessive passive income at the entity level, so you’re not entirely off the hook. Benefit corporation (B-corp) Benefit corporations allow you to pursue profit while also pursuing a public benefit that is legally defined without compromising on either. You still have shareholders, who are expecting returns, unlike a non-profit. However, your mission is legally built into your charter You can therefore prioritize social or sustainability impact, without having to worry about lawsuits by investors who are solely focused on the bottom-line. Benefit corporations can either be taxed as a C-corp, or they can elect the S-corp status based on IRS classification. It comes with additional transparency requirements such as biennial reports on your environmental or social goals. This structure also allows for greater flexibility when you are looking to raise capital and still stay true to your mission. This is the best business structure if you don’t want to choose between purpose and profit. Closed Corporation Consider this structure if you prefer less formality but want to have more control over your company. Closed corporations are exempt in many states from formalities such as the annual meeting. However, state laws vary. The ownership is also restricted to a small group of individuals, usually the founders, managers or family members. which means less outside interference but also
Bookkeeping Basics: A Guide for Small Businesses

Profit is the most important aim for all businesses, with the exception of those that are in the non-profit industry. To continue to increase profits and be prepared for the eventuality the business needs to be aware of its financial situation. This knowledge is especially crucial for smaller businesses because their capacity to handle sudden fluctuations is lower than large corporations. If you are a business owner, how do you determine your financial situation? With accurate bookkeeping. In this article, we’ll discuss the basics of bookkeeping and how to implement it, and more. What is bookkeeping? Bookkeeping is the process of recording every business transaction, such as the expense, income, asset and liability, in order to precisely assess the financial health of the company at any point. It is vital to ensure the business’s financial health, because you’ll know the amount of income and expenditure and be aware of your activities. Additionally, you are able to make informed decisions regarding your future. If, for instance, you discover a new opportunity and you want to know if you have enough money to make the most of this chance. These well-informed decisions are great for ensuring continuity in your business and growth. Keep in mind that accounting and bookkeeping can be confusing, but they’re not the same. The primary focus of bookkeeping is helping small businesses comprehend its financial standing and make more informed decisions, whereas accounting focuses on financial analysis and reporting. Why bookkeeping matters for your business Bookkeeping for small businesses is crucial to ensure the success of operations. In addition to compliance requirements, this helps companies maintain a healthy cash flow, perform precise tax calculations and meet the requirements of compliance. A few of the advantages of small business bookkeeping include: With these benefits, the importance of bookkeeping is crucial to the growth of small companies. Looking for a step-by-step bookkeeping resource? Check out our pillar guide, Bookkeeping: The Complete Guide for Business Owners, for everything you need to manage your books with confidence. The Step-by-Step Bookkeeping Process To reap the advantages above, you should have an efficient bookkeeping system. This guide will show you how to do bookkeeping for beginners: Step 1: Separate Business and Personal Expenses Regardless of your business’s structure, it’s a good idea to keep your personal and business expenses separate. This will mean that you’ll have more control over your business’s transactions and your financial health. The first step in keeping your financial affairs separate is to have different accounts for personal and business use. Be sure to set up a separate business bank account which is used exclusively for business. Also, you should use separate credit cards specifically for your business and never utilize them for personal expenses. Keep track of these expenses on your credit cards to ensure accuracy. Step 2: Choose a Bookkeeping System After you have opened the accounts, then the second step to take is to choose the business accounting and bookkeeping strategy. There are two kinds of bookkeeping: single entry and double-entry. You need to choose which one is best suited to your business. The majority of the time single-entry is a simple process that is able to record only one entry per transaction. In double-entry, each transaction impacts at minimum two accounts, one as a credit, and the second as debit. As you can see, single-entry is very easy to manage and doesn’t require special accounting expertise. But, one disadvantage is that it’s difficult to spot errors and functions effectively only for small cash flow. Based on the nature of your business and the amount of transactions, you will be able to choose the right method. In both systems, it’s recommended to utilize software for bookkeeping like QuickBooks or Xero because they come with built-in functions to automate the recording of transactions. Automating your accounting will help save time and effort as well as, maintaining the records even if you’re not an expert in accounting. Step 3: Select an accounting method – Cash vs. Accrual The next crucial decision is to make a choice between cash and accrual accounting method. Understanding the distinctions is essential. Like the name implies, with a cash account, just note a transaction when the money has been paid or received. It’s a simple system that is effective when you don’t work on credit. The accrual system, on other hand, is ideal to businesses that offer or accept credit, control inventory, or need the detailed view of their financial situation. With this method, you record the transactions when they occur, regardless of whether cash is involved at the time of the transaction or not. For example, if you provide $100 worth of goods to your regular customer by credit and they promise the opportunity to repay it within two weeks, you’ll record the transactions on the date you deliver it to the customer, not the day you receive money from the client. Out of the two methods, the accrual method is the most preferred since it offers an over-the-long term view of the financial health of a business. Additionally, the accrual method is in compliance with Generally Accepted Accounting Principles (GAAP). It is important to note that GAAP recognizes the cash basis for small businesses, as long as they meet certain requirements. Step 4: Use the right tools for bookkeeping When you are setting up your bookkeeping system, be sure to select the appropriate tools which simplify your work and help to achieve your goals over the long term. The first thing to consider is whether you’d like to make use of accounting software or just spreadsheets. While spreadsheets can be useful as well as cost effective, they may become a bit cumbersome after a certain point and they are not the best choice for recording complicated transactions. This is why an accounting software is a better flexible option that will accommodate the growing volume of transactions in your business. Additionally, It offers automated invoicing, expense tracking and reporting. This can certainly