A business personal property (BPP) rendition is the confidential yearly report you send the Tarrant Appraisal District (TAD) listing the equipment, furniture, vehicles, inventory and other income-producing property you held on January 1. It is due by April 15, and a late or missing one costs you a 10% penalty. Since voters approved the $125,000 exemption in November 2025, many small Tarrant County businesses will owe no tax on their equipment. They should still file for 2026, and after that only if their property exceeds the threshold. This guide covers who files, what goes on the form, how to file, what an extension buys you and how to protest the value TAD assigns.
TL;DR
- A rendition lists the tangible, income-producing property you owned or controlled on January 1, and it is due to TAD by April 15 each year.
- Texas voters approved a $125,000 business personal property exemption in 2025. TAD still asked businesses to file for 2026 to certify they were under the threshold.
- Filing late or not at all adds a 10% penalty. A written extension request, made by the deadline, moves the due date to May 15.
- File online at TAD.org. TAD does not accept faxed or emailed renditions.
- Disagree with the value? Protest to the Appraisal Review Board by May 15 or 30 days after your notice was mailed, whichever is later.
What a business personal property rendition is
Texas taxes tangible property that produces income, as long as it is not real estate. TAD describes BPP as every kind of tangible, income-producing property other than real estate. A rendition is the owner’s statement of that property: machinery, furniture, equipment, vehicles, merchandise and anything else in your control or possession on January 1.
The legal basis is Texas Tax Code Section 22.01. It says a person must render all tangible personal property used to produce income that they own, or that they manage and control as a fiduciary, on January 1. Renditions are confidential by law, so what you list is not published as a public record.
Two points trip people up:
- The date is a snapshot. The January 1 inventory and equipment count is what matters, not what you hold in April. Equipment you bought in February belongs on next year’s rendition.
- Leased and consigned items need thought. The statute covers property you own or control as a fiduciary. If you are unsure whether a leased copier or a customer’s consigned goods belongs on your list, ask your CPA before filing.
For the bigger picture on how Texas taxes business assets, our guide to Dallas business personal property tax explains who pays and how the bill is built.
Who has to file in Tarrant County
If you operate a business with taxable equipment, furniture, fixtures, vehicles or inventory in Tarrant County, you are in the group the law addresses. That includes:
- Restaurants, salons, medical and dental offices, and retail shops
- Contractors and service companies with tools, trucks and trailers
- Professional offices with computers and furnishings
- Manufacturers and distributors with machinery and inventory
- Landlords who furnish rental units (property that produces income)
- Nonprofits with taxable property used for income production should confirm their status with TAD and their CPA
Your property is taxed where it sits on January 1, which the statute calls its taxable situs. A Fort Worth business with a second shop in Arlington reports each location’s property under the right jurisdiction.
What changed with the $125,000 exemption
The old rule let appraisal districts skip property worth roughly the cost of administering the tax, about $2,500. Ballotpedia reports that Proposition 9 passed on November 4, 2025, with about 65% of the vote. It authorized the legislature to exempt $125,000 of the market value of tangible personal property used to produce income.
The implementing bill, House Bill 9, amends Tax Code Section 11.145 to provide that exemption for the appraised value of income-producing tangible personal property. The bill applies the exemption to each separate location in a taxing unit. Property owned by related businesses in the same unified business enterprise is aggregated at the same location.
In practice, Bracewell LLP notes that taxpayers can generally claim a separate exemption at each location they own or lease within a single taxing unit. Property at locations they neither own nor lease is aggregated and gets a single $125,000 exemption.
Here is what that means for your filing:
- Under $125,000 at a location: that property is exempt from the taxing unit’s tax. TAD said to file for 2026 anyway, to certify you are under the threshold, and that later renditions are needed only when value exceeds $125,000.
- Over $125,000: you still render, and the exemption reduces the taxable value.
- Related entities: if you own several LLCs that work as one enterprise, the aggregation rule can limit how many exemptions you get. Structure questions like this are worth a conversation with your CPA before you file.
Check TAD’s current instructions each January. The exemption mechanics, forms and wording can be updated as the district applies the new law.
What to put on the rendition
The statute sets the minimum. Section 22.01 says a rendition generally gives:
- Your name and address
- A description of the property by type or category
- For inventory, a description and a general quantity estimate of each type
- The property’s location, or taxable situs
- Your good faith estimate of market value, or, at your option, the historical cost when new and the year of acquisition
For property with an aggregate value under $20,000, the statement need only contain your name and address, a general description of the property and its location.
Two ways to value your property
TAD’s online system offers two methods, described in its online rendition guide:
| Method | What you submit | What TAD does | Best for |
|---|---|---|---|
| Historical Cost | Acquisition cost for each schedule | Calculates the depreciated value using TAD’s Percent Good chart | Most filers. TAD recommends this method |
| Good Faith Estimate | Your own calculation of total asset value for each schedule | Uses your total | Owners with solid valuation support |
If you go with a good faith estimate, expect to back it up. Another Texas appraisal district, Grayson Central, explains that a chief appraiser can require documentation of a market value estimate. A detailed list of assets with cost and year acquired works as that documentation. Appraisers also use what they see on on-site inspections.
That is why a clean fixed-asset register pays off. If your books list every asset with its purchase date and cost, the rendition takes minutes. If they do not, a bookkeeping cleanup is the first step, and the same register supports your depreciation schedules on your income tax return.
A worked example
Say a Fort Worth print shop held these items on January 1:
- Two presses, bought in 2021 for a combined $48,000
- Office furniture and computers bought across several years for $22,000
- Paper and supply inventory of $15,000
Using the Historical Cost method, the owner enters each schedule’s cost and acquisition year. TAD’s system applies its Percent Good chart to depreciate it. The numbers here are illustrative only. The point is that you supply cost and year, and the system does the depreciation math. If that location’s total stays under $125,000, the exemption applies to the taxing unit’s tax on it.
How and when to file
The deadline
Tax Code Section 22.23(a) requires renditions to be delivered to the chief appraiser after January 1 and not later than April 15. Property owners regulated by the Public Utility Commission of Texas, the Railroad Commission of Texas, the federal Surface Transportation Board or the Federal Energy Regulatory Commission have until April 30 under Section 22.23(d).
When April 15 lands on a weekend or legal holiday, TAD extends the deadline to the next regular business day. The date stays April 15 every year. Look at TAD’s site in January for the confirmed date and forms.
Where to file
Per TAD’s Business Owners page, you can:
- File online at TAD.org
- Mail the form to 2500 Handley Ederville Rd, Fort Worth, TX 76118
- Deliver it in person Monday through Friday, 8:00 am to 5:00 pm
- Use the drop box outside the front door
TAD will not accept faxed or emailed renditions. Online filing is the easiest route. The system generates a confirmation you can print, and it is also emailed to you. Keep it with your tax records.
Step by step
- In January, pull your fixed-asset list as of January 1, plus your inventory count or the year-end balance.
- Sort items by location, because the exemption and the taxing units work location by location.
- Gather cost and acquisition year for each asset class.
- Log in to TAD’s online rendition system and choose Historical Cost or Good Faith Estimate.
- Enter each schedule, review the totals and submit.
- Save the confirmation. Set a reminder for next January.
A recurring calendar entry beats memory. Our small business tax calendar guide shows how to build one that covers county, state and federal dates together.
Extensions
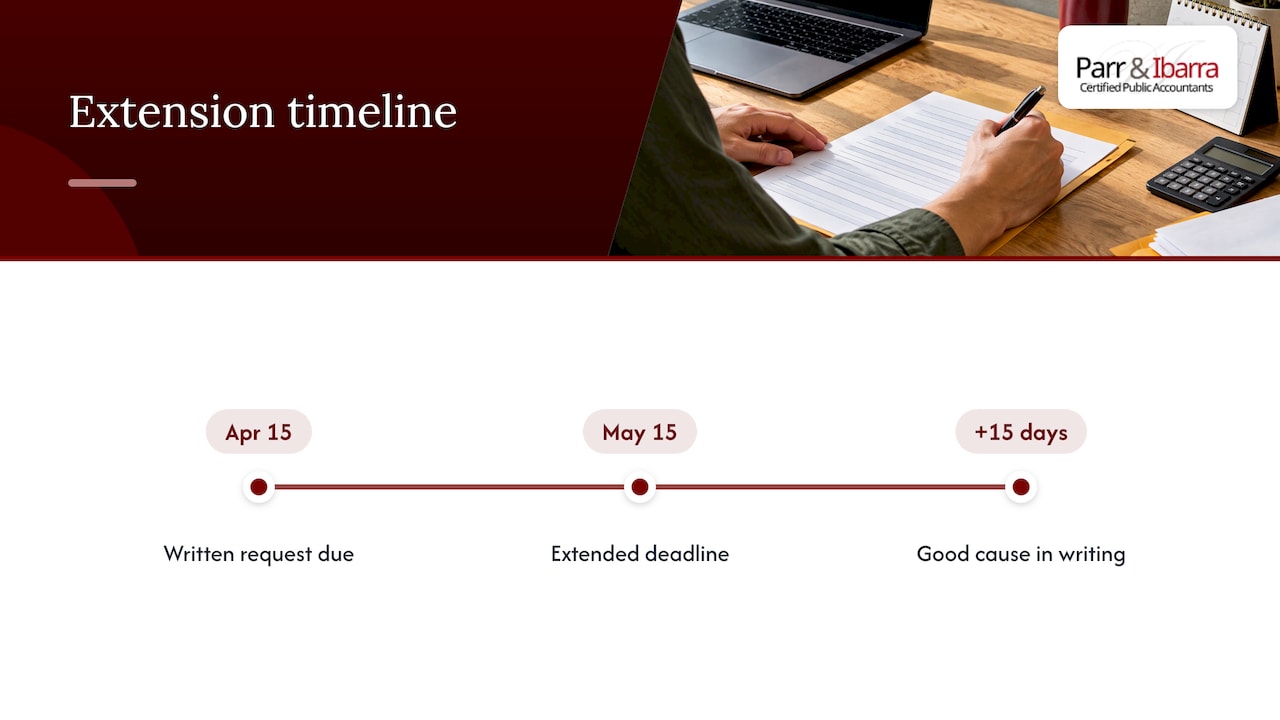
If you cannot finish by April 15, ask in writing before the deadline passes. TAD says you must request it by US Mail or through its online account service no later than April 15.
Under Section 22.23(b), the chief appraiser shall extend the filing deadline to May 15 on your written request. The chief appraiser may add another 15 days if you show good cause in writing. TAD’s online filing guide notes that the Tax Code allows only one 30-day extension for BPP renditions. Plan on a single request, and say clearly why you need the time if you ask for more.
Penalties for late or missing renditions
The Tarrant County tax office FAQ for dealers and businesses states that the law requires a 10 percent rendition penalty when an owner fails to render values on time. Questions about value, owner name, address or exemptions go to TAD, while the tax office collects.
Other consequences:
- Appraisal without your input. If an owner never files, the appraisal district uses accepted appraisal procedures to set a value, according to Grayson Central’s booklet. That value may be higher than what your records would support.
- Fraud penalty. Under Section 22.29(a), the chief appraiser imposes an additional penalty of 50 percent of the taxes if a court finally determines that a person filed a false statement or report intending fraud or tax evasion. Honest estimates made in good faith are a different matter, which is why documentation matters.
- Exemption denied or ended. If the chief appraiser denies or terminates the $125,000 exemption, the owner must render within 30 days of the denial or termination, per TAD’s BPP rendition form 50-144.
Protesting the value TAD sets
Rendition and protest are two separate steps with two separate deadlines. The rendition is your report in the spring. The protest challenges the appraised value on the notice TAD mails afterward.
TAD’s protest procedures page gives the usual deadline as not later than May 15 or within 30 days after the notice of appraised value was mailed, whichever is later. The ARB decides whether good cause exists for a late protest. The Fort Worth Star-Telegram reports that BPP owners file their notice of protest with the Tarrant Appraisal Review Board, not with the appraisal district. It also reports that an online filing starts an informal process that may settle the matter without a hearing, and that business owners should include supporting documents such as balance sheets or depreciation schedules.
What strengthens a BPP protest:
- A fixed-asset register tied to your general ledger
- Disposal records for equipment sold or scrapped before January 1
- Inventory counts as of January 1, not a later date
- Evidence of location, if property was wrongly assigned
The 2026 notices and protest windows have passed. The cycle repeats yearly, so check the date printed on your own notice.
Mistakes we see most often
- Assuming the exemption means no filing. For 2026 TAD asked businesses to file even if they expected to qualify. Check its current guidance each year.
- Using a later inventory count. The tax is based on what you held on January 1.
- Forgetting assets at a second site. Each location gets its own exemption analysis.
- Treating the extension as automatic. It needs a written request by the deadline.
- Emailing the form. TAD will not accept it that way.
How a CPA fits in
For a solo shop with a few computers, the rendition is a quick online task. It gets harder when you have several locations, related entities, heavy inventory or a gap between your books and your asset list. Our team works with Dallas-Fort Worth business owners on tax planning that treats property tax as part of the full year’s picture, along with income tax, payroll and sales tax. We can help you reconcile your fixed-asset records, decide how to value inventory and prepare support if the appraisal needs a challenge. For a wider view, see our guide to tax planning for Texas business owners in DFW.
FAQ
Do I still need to file a rendition if my equipment is under $125,000?
For 2026, TAD asked businesses to file to certify they were under the threshold. It said later renditions are needed only if value exceeds $125,000. Read TAD’s current notice each January, because the process can change.
What happens if I miss April 15?
A 10 percent penalty applies when an owner fails to render on time, according to the Tarrant County tax office. You can avoid it only by sending a written extension request by the deadline, which moves the due date to May 15.
Can I email or fax my rendition to TAD?
No. TAD does not accept faxed or emailed renditions. File online, mail it, deliver it in person during office hours or use the drop box at its Fort Worth office.
Is a rendition public information?
No. TAD states that your rendition is confidential by law. The district uses it to appraise your property.
What is the difference between a rendition and a protest?
A rendition is the report you file by April 15 listing your property. A protest is your challenge to the appraised value on TAD’s notice, filed with the Appraisal Review Board by May 15 or 30 days after the notice was mailed, whichever is later.
Sources
- TAD: File Your 2026 Business Personal Property Rendition Electronically
- Texas Tax Code, Chapter 22 (statutes.capitol.texas.gov)
- Ballotpedia: Texas Proposition 9 (2025)
- HB 9, 89th Legislature, Senate Committee Report version
- Bracewell LLP: Texas Tax Update, via Lexology
- TAD: How to File Your Online Rendition
- Grayson Central Appraisal District information booklet
- TAD: Business Owners
- Tarrant County Tax Office: FAQs for Dealers and Businesses
- Texas Tax Code Section 22.29
- TAD: BPP Rendition form 50-144
- TAD: Property Tax Protest and Appeal Procedures
- Fort Worth Star-Telegram: What to know when protesting your property value in Tarrant County